7 What a month effect is
The second fixed effect, and why this data needs one
Chapter 5 removed everything constant about a customer. One thing it did not remove is everything happening outside the customer.
Accounts are not observed over the same calendar months. If arrears drift over time — a seasonal pattern, a change in collections practice, the way this sample was assembled — then an account’s before and after sit in different conditions, and the difference between them picks that up.
Chapter 3 removed one thing per account. Now we add one thing per month:
\[ y_{it} \;=\; \beta\, x_{it} \;+\; \alpha_i \;+\; \gamma_t \;+\; \varepsilon_{it} \]
The two terms do opposite jobs. \(\alpha_i\) is one number per account, the same in every month — how risky this customer is in general. \(\gamma_t\) is one number per month, the same for every account — how bad that month was for everybody.
Why the second one is not optional here: accounts are not all observed over the same calendar months. An account’s “before” and “after” sit in different stretches of time. If the general level of arrears drifts across those stretches, part of the before-and-after difference is just the calendar moving, and the estimate charges it to the limit increase.
The model can measure that drift, because most accounts never had a limit raised. Whatever moves in them is not treatment — it is the month. Those are the same accounts that chapter 6 showed contribute nothing to the slope. Here is the job they were being kept for.
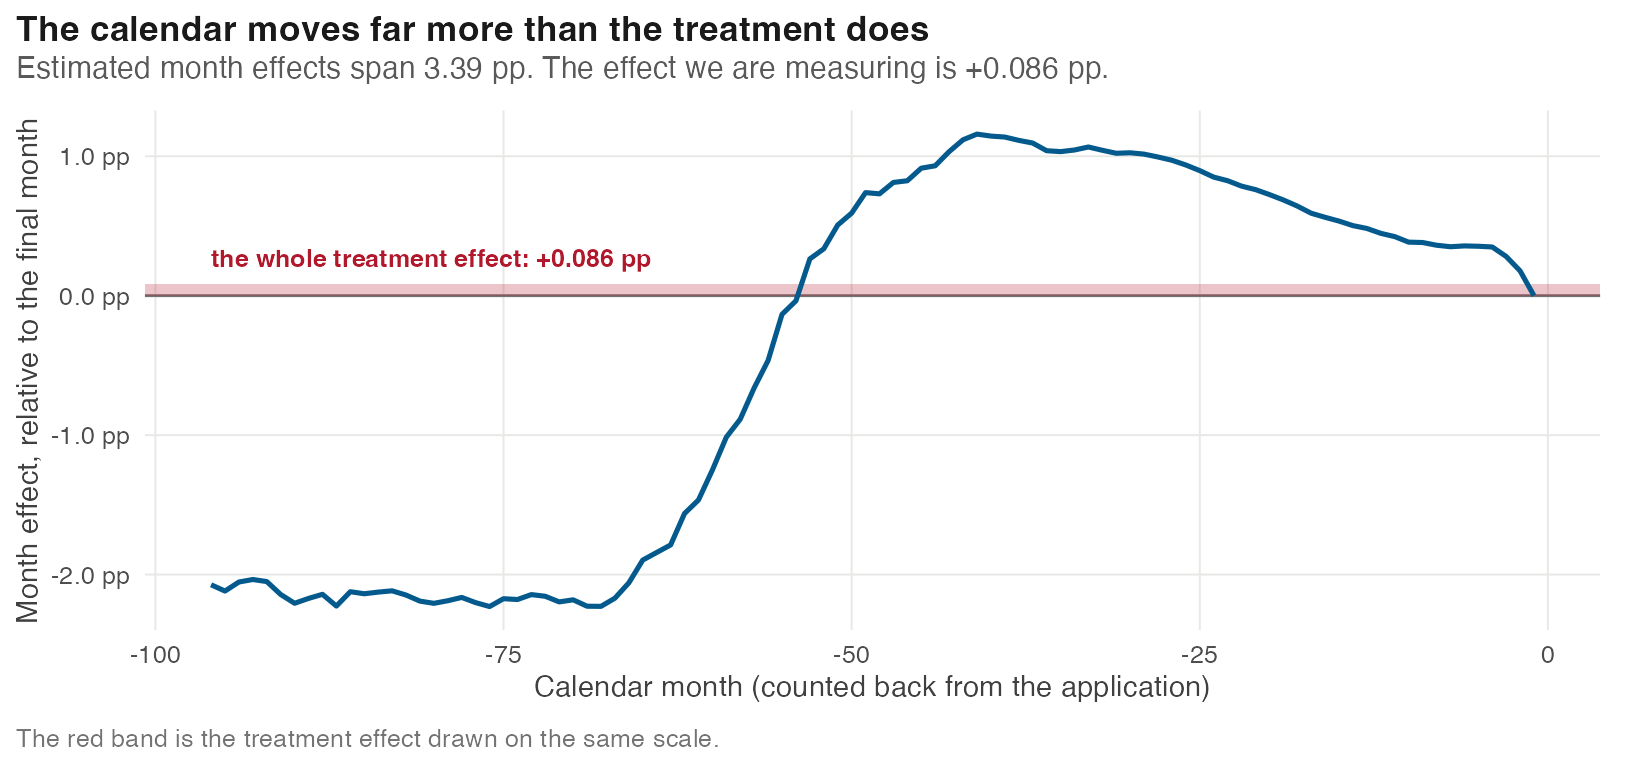
The red band is the entire thing we are trying to measure. The blue line is what the calendar does on its own, and it is 39 times larger. Leave it in the residual and it does not average away — it lands wherever the treated accounts happen to sit in time.
7.1 The second fixed effect
m_twfe <- feols(dpd30 ~ raised | SK_ID_PREV + MONTHS_BALANCE,
data = d, cluster = ~SK_ID_PREV) Model Estimate (pp) SE (pp) t
<char> <char> <char> <char>
1: Account fixed effect +0.019 0.015 1.3
2: Account + month fixed effects +0.086 0.017 5.0The estimate moves from +0.019 pp to +0.086 pp, and t goes from 1.3 to 5.0. Taking the calendar out is what makes the result stand up.
Adding it is not as simple as subtracting twice. Why not.
Where this chapter’s code lives
Everything above runs from 07-month-effects.qmd. Shared setup R/_common.R. The panel itself is built by R/01-build.R.